
Roof Insurance Claims in Ohio: What Homeowners Should Expect
September 14, 2026
•
Written By
4 Seasons Construction & Roofing
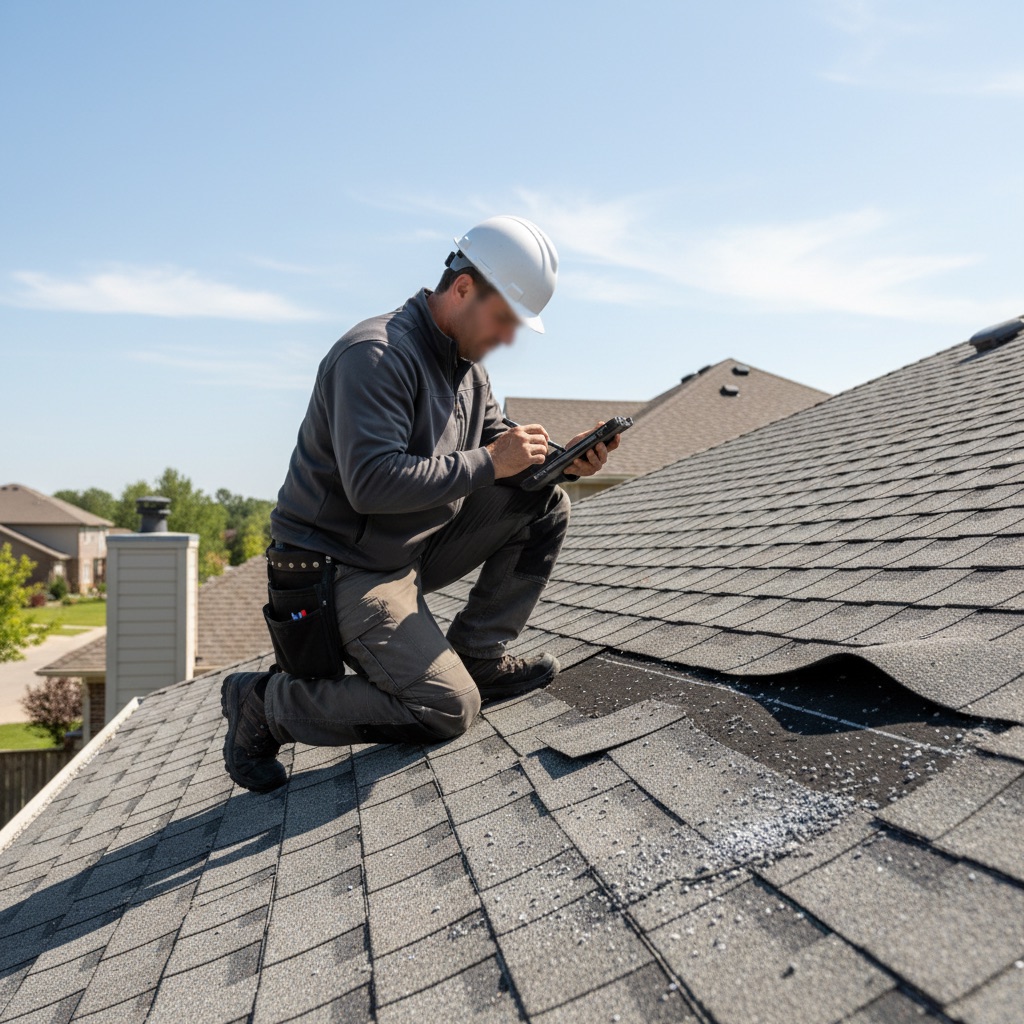
A roof insurance claim in Ohio generally covers sudden, accidental damage from events like wind, hail, or a fallen tree, but not wear and tear or age. The process moves through a few clear steps: document the damage, file the claim, meet the adjuster, and complete the approved repairs with a licensed contractor. Knowing what to expect keeps you in control and reduces the stress of an already stressful moment.
At 4 Seasons Construction & Roofing, we have guided Northeast Ohio families through this since 1986. As a preferred contractor for major insurers including Westfield and Travelers, we help homeowners understand the process honestly, without the high-pressure tactics that give roofing a bad name.
Key Takeaways
- Insurance typically covers sudden storm damage, not gradual wear, age, or neglected maintenance.
- Documenting damage with photos and dates strengthens your claim before the adjuster arrives.
- A reputable contractor can meet your adjuster and make sure the scope reflects the real damage.
- Be wary of anyone who offers to waive your deductible or promises a free roof, which are red flags.
What roof damage does homeowners insurance cover in Ohio?
Most Ohio homeowners policies cover roof damage caused by sudden, accidental events, often called perils. In Northeast Ohio the common ones are wind, hail, and damage from falling trees or limbs during a storm. If a covered event damages your roof, the policy generally helps pay to restore it.
What insurance usually does not cover is deterioration over time. A roof that is simply old, poorly maintained, or worn out is considered a homeowner responsibility, not an insurable loss. This is one reason keeping up with maintenance and inspections matters, because it preserves both your roof and your coverage.
Policies also differ in how they pay. Some reimburse the actual cash value, which factors in depreciation, while others pay replacement cost value, which covers the cost to replace the roof up to your limits. Reading your policy or asking your agent to explain these terms is worth the time before a storm ever hits.
How does the roof insurance claim process work?
The claim process is more manageable when you know the sequence in advance. Here is how a typical Northeast Ohio roof claim unfolds.
- Document the damage. Take clear photos and note the date of the storm. Do not climb an unsafe roof; a contractor can inspect it for you.
- Get a professional inspection. A licensed roofer assesses the damage and tells you honestly whether it rises to the level of a claim.
- File the claim. Contact your insurer promptly and provide your documentation. Ohio claims are subject to time limits, so do not wait.
- Meet the adjuster. The insurance adjuster inspects the roof to confirm the damage and scope. Your contractor can be present to make sure nothing is missed.
- Complete the repairs. Once the claim is approved, your chosen contractor completes the work and coordinates any supplements if hidden damage appears.
Throughout this process, you remain the decision-maker. A trustworthy roofer supports your claim with facts and documentation, but never pressures you or inflates the damage to chase a bigger job.
How does a contractor help with an insurance claim?
A good contractor makes the claim smoother by translating between the roof and the paperwork. They inspect and document the damage in the detail an adjuster expects, which helps the approved scope match what your roof actually needs.
Being present for the adjuster meeting is one of the most valuable things a contractor does. Roof damage can be subtle, and an experienced local roofer can point out hail bruising, wind-lifted shingles, or flashing damage that is easy to overlook. This protects you from an under-scoped approval that leaves real damage unaddressed.
After approval, the contractor handles the roofing work and any supplemental requests if the tear-off reveals damage that was not visible from the surface. If your situation is urgent, prompt emergency roofing protection can prevent further interior damage while the claim proceeds.
What are the warning signs of insurance fraud?
The roof insurance process attracts a small number of bad actors, and knowing their tactics protects you. Be cautious of any contractor who does the following.
- Offers to waive, cover, or pay your deductible. This is illegal in many situations and can void your claim.
- Promises a free roof or guarantees your claim will be approved before inspecting anything.
- Pressures you to sign an assignment of benefits or contract on the spot.
- Cannot show a local address, license, or insurance.
The Ohio Department of Insurance and consumer advocates consistently warn that post-storm roofing scams rise after major weather events. A legitimate local contractor gives you time, answers your questions, and lets the facts of your roof drive the claim.
Why choose a local contractor for an insurance claim?
A local contractor brings accountability that an out-of-town crew cannot. When 4 Seasons Construction & Roofing helps a family in Chagrin Falls or Chardon through a claim, we are still here afterward to stand behind the work and answer questions.
Our long relationship with insurers, including our preferred-contractor standing with Westfield and Travelers, means we understand what documentation adjusters look for and how to keep a claim moving. That experience benefits you, but it never changes our approach, which is to represent the honest condition of your roof and nothing more.
Most of all, a local family roofer treats your claim the way we would want our own handled. You get straight answers, careful documentation, and quality work, without the pressure.
Frequently Asked Questions
Will filing a roof claim raise my insurance rates?
A single weather-related claim may or may not affect your premium, and rate practices vary by insurer. Weather claims are often treated differently than liability claims. Ask your agent about your specific policy before deciding, and weigh the cost of the repair against your deductible.
How long do I have to file a roof insurance claim in Ohio?
Ohio policies include time limits for filing, and many insurers expect prompt reporting after the damaging event. Do not delay. File as soon as you have documented the damage, and confirm the specific deadline with your insurer or agent.
Should my contractor meet the insurance adjuster?
Yes, when possible. Having your contractor present helps ensure the adjuster's scope reflects all the real damage, including subtle hail or wind damage that is easy to miss. It protects you from an approval that under-scopes the repair.
What if my roof claim is denied?
A denial is not always final. You can request a re-inspection, provide additional documentation, or ask for a second adjuster review. A licensed contractor can help you document the damage clearly to support a reconsideration.
Get Honest Guidance on Your Roof Claim
Facing storm damage in Northeast Ohio? Call 4 Seasons Construction & Roofing at (440) 286-1618 for an honest inspection and clear, no-pressure guidance through your insurance claim.
Recent Articles
Residential Roofing
Roof Insurance Claims in Ohio: What Homeowners Should Expect
A calm, honest walkthrough of the roof insurance claim process for Northeast Ohio homeowners, from documenting damage to working with your adjuster and contractor.
September 14, 2026
Residential Roofing
How Ohio Winters and Lake-Effect Snow Affect Your Roof
A Geauga County homeowner's guide to how lake-effect snow, ice dams, and freeze-thaw cycles stress your roof, and the steps that keep it protected all winter.
September 14, 2026
How to Choose a Local Family Roofer in Northeast Ohio (and Spot a Storm Chaser)
How Northeast Ohio homeowners can tell a trustworthy local family roofer from a door-knocking storm chaser, and the questions that reveal the difference.
September 14, 2026
Residential Roofing
Cost to Replace a Roof in Geauga County: A 2026 Homeowner's Guide
A clear, honest look at what a roof replacement costs for Geauga County homeowners in 2026, the factors that change the price, and how to plan for the investment.
September 8, 2026